
News
From confidence to success: how We Fi and the EBRD support women entrepreneurs through the MicroMentor platform
Promoting local tourism through the MicroMentor platform
24 Sep 2026

 Eng
 Eng
Growth in the economies where the European Bank for Reconstruction and Development (EBRD) invests is expected to slow to 2.5 per cent in 2026, before picking up to 4.0 per cent in 2027, according to the Bank’s latest Regional Economic Prospects.
The 2026 growth forecast has been revised down by 0.6 percentage points relative to the previous forecast published in June, while the 2027 outlook has been revised up by 0.4 percentage points.
The revisions largely reflect a deep recession in Iraq where oil exports have collapsed, followed by an expected rebound once oil shipments normalise. Excluding Iraq, this year’s forecast has been revised down by 0.1 percentage point, reflecting tighter financing conditions, the impact of drought in Europe and the Black Sea shipping blockade, while the outlook for 2027 is unchanged.
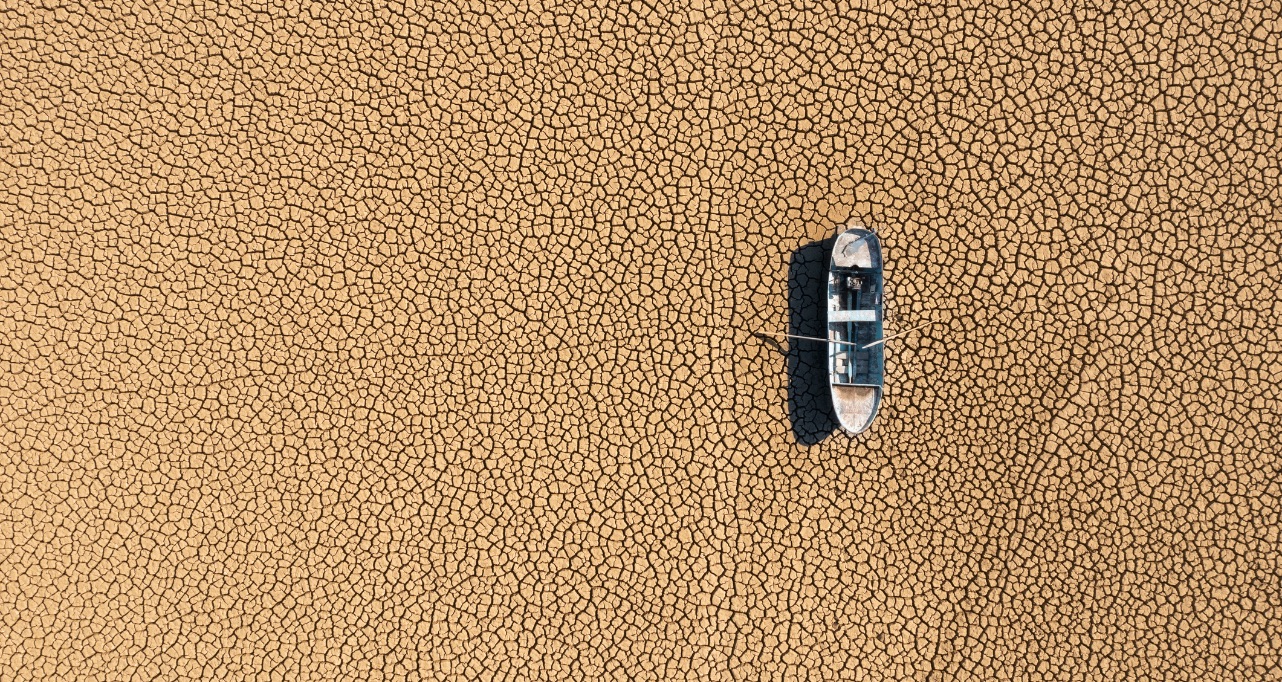
The report, entitled “Running dry”, highlights growing constraints in three key areas: oil exports, water and global savings. Together, these pressures are exposing vulnerabilities in energy systems, food supply chains and financing conditions across the EBRD regions.
Oil prices climbed from around US$ 65 a barrel before the conflict in the Middle East to more than US$ 100 by April 2026, as seaborne crude exports from the region halved. Prices remain 30 to 60 per cent above their pre-conflict level. Refined products, particularly diesel and jet fuel, have seen larger price increases than crude.
The impact on import bills varies across economies, with Bosnia and Herzegovina, North Macedonia and Moldova facing the largest increases owing to their high dependence on energy imports and indirect exposure to the Middle East through oil-product supply chains.
Gas markets have also tightened. Gas prices have risen by more than 70 per cent since February, while global exports of seaborne liquefied natural gas have fallen by 40 per cent as Middle Eastern cargoes have largely stopped. Gas storage in the European Union (EU) was only 65 per cent full in August, its lowest level for that month in 15 years; it is unlikely to reach the 90 per cent pre-winter refill target at the current injection rate.
Food supplies have also been affected. Grain shipments from Ukraine and Russia through the Black Sea have been severely disrupted by military attacks on infrastructure and vessels, as Russia’s invasion of Ukraine has entered a new stage of escalation.
The report highlights that Russia and Ukraine together account for around a quarter of global wheat exports, and prolonged disruption could have consequences well beyond the EBRD regions. Wheat prices have risen by more than a third and are expected to remain elevated through 2028, while higher fertiliser prices are likely to feed more fully into farm costs in 2027.
Ukraine’s ability to reroute grain exports has been further constrained by low water levels on the River Danube. Indeed, drought has been particularly pronounced in central Europe and the Baltic states – 38 per cent of land was at medium or high agricultural drought risk in 2026, compared with an average of 12 per cent since 2010.
These record-low water levels in both the Danube and Rhine rivers have weighed heavily on shipments of industrial goods and on energy generation, cutting output from hydropower and nuclear plants by around a third. The resulting rise in electricity prices across interconnected markets underlines the growing economic importance of water availability alongside energy security.
“The shocks facing economies across the EBRD regions show no sign of abating,” said Beata Javorcik, the EBRD’s Chief Economist. “Water scarcity, extreme weather and higher financing costs are compounding the effects of high energy costs, putting further pressure on growth. This underlines the urgency of investing in resilience and strengthening our economies to better withstand the shocks that may lie ahead.”
Average inflation in the EBRD regions has stabilised at around 6 per cent after reaching 6.7 per cent in April. Energy accounts for around a quarter of headline inflation, with limited pass-through to other components. Inflation remains around two percentage points above its pre-Covid average and is increasingly feeding into higher inflation expectations.
At the same time, financing conditions have tightened. National saving rates in advanced economies have been falling, while higher inflation and government deficits, combined with increased corporate borrowing for investment in artificial intelligence, have pushed longer-term interest rates higher.
Government bond yields across most EBRD economies have risen alongside those in advanced economies, even as sovereign spreads over Germany have generally returned to or fallen below pre-conflict levels. Fiscal space is particularly constrained in Egypt and Kenya, where interest payments absorb more than 30 per cent of government revenue.
The EBRD regions also remain structurally exposed to volatile fossil-fuel prices. Oil and gas account for around two-thirds of primary energy use, while renewables and nuclear provide more than half of electricity generation in the EBRD economies in the EU, but only around a quarter elsewhere in the EBRD regions. Reducing reliance on gas will require further investment in renewables, energy storage and nuclear power.
High energy costs are weighing on European industry. Firms in the EU pay around 2.4 times the US price for electricity, encouraging a shift away from energy-intensive production.
Trade conditions have become somewhat less restrictive following changes to US tariffs in July, which reduced the average statutory tariff on imports from the EBRD regions from 11.6 to 8.6 per cent, with reductions for 34 of the Bank’s 40 economies. However, frequent changes to tariff regimes have kept trade-policy uncertainty elevated.
Growth in central Europe and the Baltic states is expected at 2.9 per cent in 2026 and 2.5 per cent in 2027. Economic activity has been supported by a peak in the absorption of EU Recovery and Resilience Facility funds, but growth is expected to moderate as this financing comes to an end. Slovenia’s 2026 forecast has been revised up on stronger investment related to post-flood reconstruction.
In the south-eastern EU, growth is projected at 0.5 per cent in 2026 and 2.0 per cent in 2027, unchanged from the previous forecast. Growth has been held back by a contraction in Romania, where fiscal consolidation and high inflation have weighed on household spending, alongside weaker manufacturing output. In Bulgaria, growth has held up at close to 3 per cent.
Growth in the Western Balkans is expected at 3.0 per cent in 2026 and 3.5 per cent in 2027, supported by improving external demand, stronger investment and tourism.
In Central Asia, growth is forecast at 5.8 per cent in 2026 and 5.3 per cent in 2027. Forecasts have been revised up for Uzbekistan on strong domestic demand, and for Mongolia, on record mining output. Disruption to fuel supplies from Russia remains a downside risk.
In eastern Europe and the Caucasus, growth is expected at 2.5 per cent in 2026 and 3.1 per cent in 2027. Forecasts for Ukraine have been revised down following Russia’s renewed attacks on Ukraine’s Black Sea ports and vessels, while Georgia’s forecasts have been revised up on broad-based growth.
In Türkiye, growth is projected at 3.0 per cent in 2026 and 4.0 per cent in 2027. The 2026 forecast has been revised down by 0.5 percentage points as persistent inflationary pressures have required tighter financing conditions.
Growth in the southern and eastern Mediterranean is forecast at -0.7 per cent in 2026 before rebounding sharply to 7.1 per cent in 2027, driven largely by the expected normalisation of Iraq’s oil exports. Excluding Iraq, growth is projected at 3.9 per cent in 2026 and 4.3 per cent in 2027. Lebanon remains in recession following renewed military escalation and infrastructure damage, while forecasts for Morocco and Tunisia have been revised up on strong agricultural output.
In sub-Saharan Africa, growth is expected at 4.8 per cent in 2026 and 4.7 per cent in 2027 as commodity windfalls fade. The 2026 forecast has been revised up, mainly on stronger growth in Nigeria, supported by agriculture and services, and by rising output at the Dangote refinery, which has reduced fuel imports.